PROP HOURS BLOG
The 100-Hour Trap: Property Managers and STR Tax Deductions
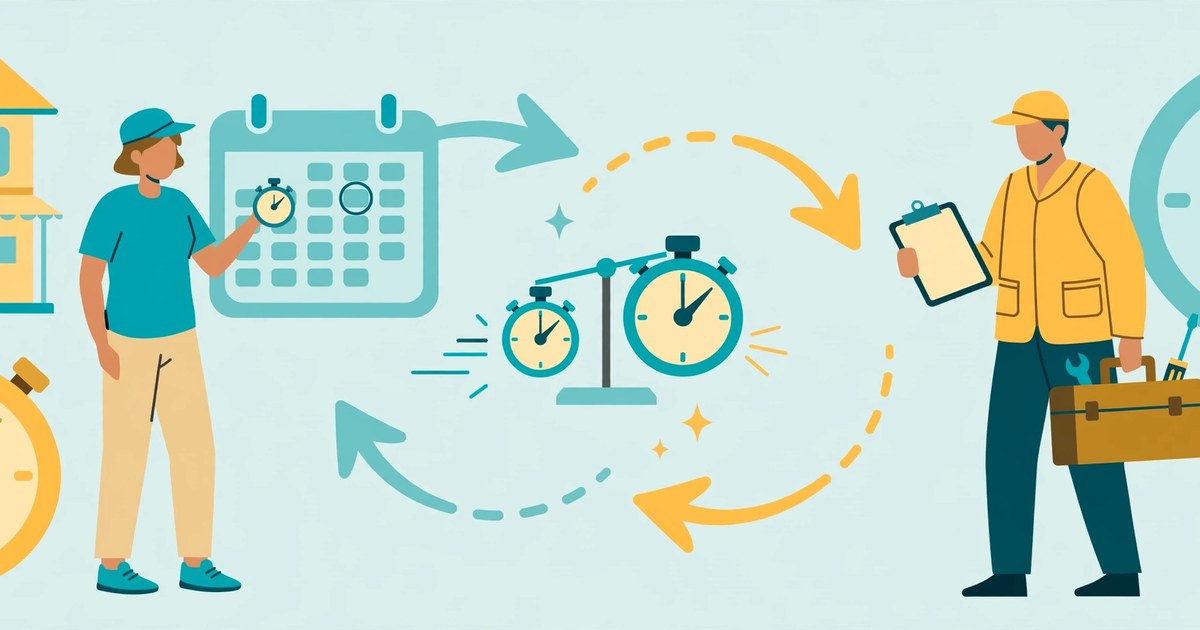
You logged 128 hours on your short-term rental this year. You cleared 100 — except your property manager logged 150, and under the 100-hour test the other side of the scale counts as much as yours. The test has two halves: more than 100 hours of your own participation, and no other individual participating more than you. Plenty of STR owners clear the first half and silently fail the second. Here is how the trap works and five ways to escape it.
The two halves of the 100-hour test
Most owners know the first half: participate for more than 100 hours in the activity during the year. Note the word more — exactly 100 hours is not enough. Aim past the line, not at it.
The second half gets less attention, and it is the one that ends deductions: your participation must be not less than the participation of any other individual. In plain English, nobody else can do more than you. "Any other individual" means everyone — not just co-owners. Your property manager, your co-host, your cleaner, your handyman: all of their hours sit on the comparison side. The test is a race, not a quota, and you have to win it.
This is the test most STR owners reach for — paired with the 7-day rule, it is the lowest-bar path to non-passive losses. Our full guide to the 100-hour material participation test walks through the mechanics in detail.
Why your property manager is the other side of the scale
A property manager's hours are never your hours. That much is obvious. The subtle part is how much weight those hours carry: under the comparison half, every hour your manager works is an hour you have to beat.
Full-service managers routinely log 200 to 400 hours a year on a single property — guest communication, turnover supervision, maintenance dispatch. An owner with a W-2 job who works the property on nights and weekends might log 120 to 180. The result is obvious: 150 honest, documented hours against 250 of theirs is a failed test.
There is a second problem. The regulations generally exclude management services from your participation when another person is compensated for managing the activity. So the hours you spend supervising your manager — the weekly check-ins, the approvals, the oversight — may not count on your side at all, while the manager's hours count fully on the other side. You lose twice: your total shrinks and the comparison grows.
None of this means managers are the enemy. It means the 100-hour test and a full-service manager are usually a bad combination — one of them has to change.
The math: a tale of two owners
Maya owns a two-bedroom cabin on two platforms. In year one she hires a full-service manager and stays involved: 128 hours of guest messaging (40), dynamic pricing (20), coordinating vendors (30), and restocking plus minor repairs (38). Her manager logs 150 hours.
Maya clears the first half easily — 128 is more than 100. But 150 beats 128, so the second half fails. If she claimed the losses as non-passive, an examiner with the manager's invoices in hand would have the whole case in one comparison.
In year two Maya restructures instead of working more. She keeps a turnover-only cleaner (60 hours for the year), takes guest messaging and pricing back herself, and handles vendor coordination directly. Her total rises to 175; the cleaner's 60 and the handyman's 25 are the only other entries. Now 175 beats 100 and beats every other individual. Same owner, similar effort — passing test.
The lesson is the whole article in one sentence: the 100-hour test is a comparison, not a quota. Shrinking the other side works just as well as growing yours.
What the regulation actually says
The 100-hour test comes from the temporary regulations under §469. Paraphrased carefully, it provides two conditions: the individual participates for more than 100 hours during the year, and the individual's participation is not less than the participation of any other individual — including individuals who own no interest in the activity.
Two related rules complete the picture. First, the management-services exclusion: time spent on management generally does not count toward your total when another person is paid to manage. Second, only work of a type customarily done by an owner counts — and your spouse's participation is generally attributed to you, so a spouse's hours help rather than hurt.
Notice what is not in the rule: no required share of the total, no minimum beyond 100, no carve-out for the professionals you hired. The comparison includes everyone you pay.
Five ways out of the trap
1. Do more of the real work yourself. Guest communication, pricing, listing management, vendor coordination, operational bookkeeping — these are the hours that count. Move tasks from your manager's column to yours and both sides of the comparison move in your favor.
2. Unbundle the manager. Keep a cleaner for turnovers only — their annual hours stay small — and take the judgment-heavy work back. A 60-hour cleaner is a comparison you can beat; a 250-hour manager is not.
3. Watch the cleaner's hours too. In high-turnover STRs, turnover cleaning adds up fast — three turnovers a week can quietly pass 100 hours a year. Track their invoices the way you track your own time; you cannot win a comparison you are not measuring.
4. Consider the 500-hour test. It has no comparison side at all: more than 500 hours of your own participation and you are done. Hands-on hosts who self-manage everything often get there. Volume replaces the race.
5. Look at the other tests. The facts-and-circumstances test rewards regular, continuous, substantial participation without a head-to-head comparison; the substantially-all test fits solo operators with minimal outside help. Our seven plain-English guides cover each one — the 100-hour test is only one of seven doors.
The logging checklist
Winning the comparison on paper is only half the job; proving it is the other half. Your file needs two parts. First, your contemporaneous hour log: dated entries showing what you did, for which property, and for how long — made when the work happened, not reconstructed the following April. Timers, voice notes, and attached receipts (the PropHours workflow) are built for exactly this. Second, a third-party file: the manager or co-host agreement, cleaner invoices with dates, handyman bills. This proves the comparison side instead of merely asserting it — and it is what lets your CPA verify that nobody did more than you.
Finally, build in margin. A log that shows 175 hours with a third-party file showing 85 is a defensible claim. A log that shows 101 with no third-party file is a dare. Aim for 130 to 150 at minimum — the cushion is the strategy.
My manager logged 150 hours and I logged 128. Can I still pass the 100-hour test?
No. The test requires more than 100 hours and participation not less than any other individual's. Your 128 clears the first half but loses the comparison. Either increase your own hours, shrink the manager's role, or aim for a different test such as the 500-hour test.
Do the hours I spend supervising my property manager count?
Often not. The regulation generally excludes management services from your participation when another person is compensated for managing the activity. Build your hours from operational work — guest relations, pricing, maintenance decisions, bookkeeping — and discuss the mix with your CPA.
What if my cleaner and I tie at 110 hours each?
The test only requires your participation to be not less than any other individual's, so a true tie meets the letter of the rule. But a tie proved by reconstructed year-end estimates is a fragile position — give yourself a real margin and document both sides.
Is firing my property manager the only way to use this test?
No. Many owners keep a turnover cleaner and take back guest messaging, pricing, and vendor coordination themselves. Others aim for the 500-hour test, which has no comparison side, or one of the other five tests. The right answer depends on your hours and your team.
How do I prove nobody did more hours than me?
Keep two files: your contemporaneous hour log, and a third-party file with cleaner invoices, handyman bills, and manager or co-host agreements. That combination lets your CPA verify the comparison instead of asserting it — which is exactly what an examiner would ask for.
Related reading
Master the test itself in our 100-hour material participation test guide, see how it fits the bigger picture in the short-term rental tax loophole guide, and compare all seven options in our material participation guides.
This article explains the 100-hour test under Temp. Reg. §1.469-5T in general terms and is not tax advice. Whether you meet the test depends on your facts; review IRS Publication 925 and consult a qualified tax professional. PropHours records the work you log — it does not determine tax eligibility.